

Money App - Cash Advance
PRG Ventures.
- 4.2
- 2.43K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
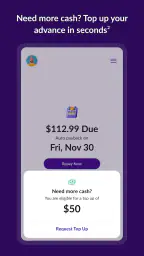
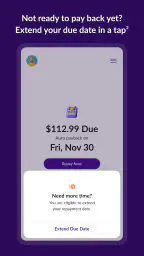
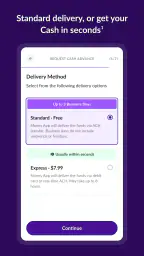
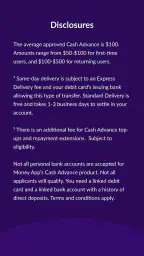
Money App - Cash Advance Pros and Cons
Pros
- Simple application process with minimal paperwork required
- Clear repayment terms help users understand their borrowing obligations
- Useful for handling unexpected short-term expenses
- Application can be completed from a mobile device
- May show eligibility before finalizing a request
Cons
- Cash advance fees can make borrowing expensive
- Approval and funding are not guaranteed for every applicant
- Repayment deadlines may be difficult for users with limited income
- Availability and terms can vary by state or location
- Requires sharing sensitive financial and personal information
 Analysis by All-app
When an unexpected expense lands between paydays, the appeal of Money App - Cash Advance is easy to understand. It is a finance app from PRG Ventures built around access to emergency cash, and it is free to install for everyone. I approached it less like a general budgeting tool and more like a short-term financial option to examine carefully before relying on it. That distinction matters: an app that helps in a tight moment should also encourage calm decisions, not make borrowing feel casual.
My overall impression is mixed but useful. The app is straightforward to consider when a sudden bill cannot wait, yet it is not a replacement for savings, a bank account, or a long-term debt plan. The experience also depends heavily on having a working mobile connection at the moments when you need to sign in, review information, or continue an application. For someone comparing emergency options on a phone, that connectivity factor is just as important as the headline promise of cash access.
How Money App fits an urgent cash decision
I see this as an app for a narrow situation: you have a genuine short-term gap and want to explore whether an advance may help. That could mean a necessary household purchase, a bill with an immediate deadline, or a transport problem that affects work. The useful mindset is to treat the app as one possible route, not as money that is already guaranteed.
That difference prevents one of the most common mistakes with emergency-finance products. Opening an app and completing an initial step does not automatically mean the final outcome will suit your needs. I would first write down the exact amount required and the date by which it must be resolved. Then I would compare the app’s eventual terms with alternatives I already understand. Borrowing more than the immediate problem requires can turn a small interruption into a longer repayment burden.
The app has attracted a sizeable audience, with more than half a million installs and an average rating of 4.2 from around ten thousand ratings. Those figures suggest that many people find the concept useful, but they should not be treated as a personal recommendation or as evidence that every applicant will have the same experience. Finance apps are especially sensitive to individual circumstances, eligibility, timing, and the details shown during the process.
I also appreciate that it is free to download. That removes one barrier to comparing options, although “free” should not be confused with “cost-free borrowing.” Before accepting anything, I would read every repayment detail, any applicable charge, and the timing involved. If the final cost is unclear on the screen, I would pause rather than proceed simply because the need feels urgent.
What I would check before starting
My first preparation would be practical rather than technical. I would make sure the phone has enough battery, use a private connection I trust, and have the information normally needed for a financial application close at hand. I would also avoid starting while rushing through a checkout line or standing somewhere noisy. A few minutes of focused attention can make it easier to notice repayment dates and conditions that are easy to overlook when stressed.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The app is rated for Everyone, which makes it broadly accessible as a mobile product. That label does not remove the need for adult financial judgment. A person who is already behind on several obligations should be particularly cautious, because another advance may only move the pressure forward. In that situation, speaking with a bank, creditor, community adviser, or trusted financial professional may be more appropriate than opening another borrowing channel.
Why connectivity changes the experience
Emergency finance is unusually sensitive to network quality. A slow connection can make a normal screen feel uncertain: a button may appear not to respond, a page may take longer to load, or a confirmation may be delayed. I would not repeatedly tap a submission control just because the screen has paused. That can create confusion about whether an action was sent once or several times.
A stable connection is also important for reviewing current information. Financial screens can contain changing details, and I would want the app to load completely before making a decision. If I were using public Wi-Fi, I would be more cautious about entering sensitive information and would prefer a trusted mobile connection or home network. The convenience of handling an urgent request in a café or on public transport is real, but convenience should not outweigh privacy.
This network reliance affects when I would use it. If I had only a few minutes before a payment deadline, I would not make this my sole plan. I would keep a second route in mind, such as contacting the bill provider, checking an existing bank facility, or asking whether the due date can be adjusted. That is not a criticism unique to this app; it is a sensible safeguard whenever a financial decision depends on a live mobile service.
Using it in everyday mobile situations
The most realistic use case is a person discovering an urgent expense during an ordinary day. Imagine a work commute interrupted by a necessary repair or a household bill arriving earlier than expected. The phone is already the person’s main tool, so a finance app feels faster than searching through paperwork or waiting until reaching a desktop computer. Money App can fit that mobile habit, especially for someone who wants to inspect an emergency-cash option without paying an installation fee.
Still, I would not complete the process while distracted. On a bus, in a crowded shop, or during a work break, it is easy to skim instead of read. My better workflow would be to use the phone to begin the research, then move somewhere quiet before reviewing the important details. If the connection becomes unreliable, I would stop and note where I was rather than guessing that the process had completed.
Another practical situation is a user with limited time and limited data. Loading multiple screens, returning to earlier steps, or restarting after a failed connection can consume both. I would avoid switching repeatedly between cellular data and unstable Wi-Fi. I would also keep screenshots or written notes only where doing so is safe and does not expose sensitive personal information. The goal is to remember the terms, not to create unnecessary copies of private financial details.
What happens when the connection fails
The most frustrating moment with any urgent financial app is a failure after information has already been entered. A frozen page does not tell you whether the request was rejected, delayed, or simply waiting for the network. My advice is to wait briefly, check the connection, and look for a clear status or confirmation before trying again. If the app returns to an earlier screen, I would carefully review what has already been submitted instead of assuming that nothing happened.
I would also keep a simple record of the time of an attempted action and any reference or confirmation shown on screen. That is a useful habit with financial services because it gives you something concrete to refer to if you need help later. It is better than relying on memory, especially when the situation is stressful.
A recovery plan should include an alternative way to handle the original expense. If the bill is urgent, contact the provider directly rather than waiting indefinitely for the app. If the money is needed for transport, food, or another essential, consider whether a trusted person or an existing account option can bridge the gap without creating a new obligation. The app may be convenient, but convenience should never be mistaken for certainty.
When the app works normally, the mobile format can reduce friction compared with visiting a branch. When it does not, the same compact design can leave less room to understand what went wrong. That is why I value patience here more than speed. A rushed second attempt may be worse than taking a moment to verify the first one.
Keeping mobile data and privacy in mind
Because this is a finance app, I would use it with the same care I apply to mobile banking. I would keep the operating system updated, use a screen lock, and avoid handing the unlocked phone to someone else while an application is open. I would not enter sensitive information on a network I do not trust merely because the need feels urgent.
Data-conscious use also means reducing unnecessary repetition. If a page fails, restarting the entire process several times may use more data and create more uncertainty than waiting for a stable connection. I would close unrelated apps, move to a stronger signal, and continue only when the screen behaves normally. On a limited mobile plan, that small bit of preparation can make the session more predictable.
I would read the app’s current privacy and permission explanations before proceeding, rather than accepting every prompt automatically. Financial information deserves deliberate handling, and I prefer to understand why an app requests access before allowing it. If a request seems unrelated to the task, I would stop and investigate. This is a general privacy principle, but it is especially important when the product deals with emergency cash.
There is also a human side to data awareness. A person may be tempted to use someone else’s phone or network when their own connection fails. I would avoid that unless I could protect the account properly and sign out completely afterward. A short-term cash problem should not create a separate account-security problem.
How it compares with familiar alternatives
Compared with visiting a traditional bank branch, the app is more convenient for someone who wants to explore an option from a phone and does not want to pay for the download. A branch may offer a more personal conversation, however, which can be valuable when the financial situation is complicated. A bank account or existing credit facility may also be easier to understand if the user already knows its terms.
Compared with asking a bill provider for extra time, an advance can appear faster, but it may introduce a new repayment responsibility. Contacting the provider first is often the better choice when the problem is a deadline rather than a permanent lack of funds. That route may not solve every situation, but it can avoid borrowing for an expense that could have been rescheduled.
Compared with a budgeting app, Money App has a different purpose. Budgeting software helps identify patterns and prepare for future shortfalls; this app is aimed at the immediate cash gap. I would not choose it as my main tool for building savings or tracking monthly spending. If the same emergency keeps happening, the more useful long-term solution is to examine income, fixed costs, and timing rather than repeatedly seeking advances.
Compared with informal borrowing from family or friends, the app may feel more private and independent. Informal help can also carry emotional complications, while a formal financial product has its own conditions and consequences. The right choice depends on what the user can repay and what terms are clearly understood. There is no universally safest option without looking at the actual circumstances.
Who should consider it, and who should skip it
I think the app is most suitable for someone who has a specific, short-lived cash shortage, can review terms carefully, and has a realistic plan for repayment. It may also suit a person who prefers handling financial tasks on a phone and wants to compare an emergency option without an upfront download charge. The free price makes initial comparison easier, while the broad age rating keeps the app accessible to a wide audience.
I would skip it if I needed guaranteed money immediately, because a mobile application cannot remove eligibility or timing uncertainty. I would also be cautious if I had no clear way to repay the advance, if I was already juggling several debts, or if the proposed amount exceeded the actual emergency. In those cases, the app could provide temporary relief while worsening the underlying problem.
It is also not the best choice for someone who dislikes reading financial conditions on a small screen. A branch appointment or direct conversation with an established financial provider may be slower but easier to discuss. Likewise, a user with unreliable connectivity should not depend on this as the only emergency plan.
My practical way to approach the app
I would begin by defining the need, checking the connection, and opening the app when I could concentrate. I would read each screen instead of treating the process as a quick form. Before accepting an offer, I would compare the total obligation and repayment timing with the cost of doing nothing, asking for more time, or using an existing financial option.
If I encountered a loading problem, I would avoid duplicate submissions and preserve any confirmation details. If the app did not provide a clear outcome, I would seek support through the appropriate in-app route or use another solution for the original expense. Most importantly, I would not let the pressure of an urgent bill push me into agreeing to something I could not explain in my own words.
The current release is version 2.47.0 and requires Android 7.0 or later, so compatibility is worth checking before planning around it. The app has been available since February 12, 2024, and its growing install base shows that the emergency-cash concept has reached many mobile users. Those details help establish what kind of product it is, but they do not replace reading the terms presented to an individual user.
Final connectivity verdict
Money App - Cash Advance is worth considering when a defined short-term emergency makes a mobile financial option useful, especially for someone who wants a free download and can make decisions carefully. Its biggest practical strength is convenience: the phone is already with you when an unexpected expense appears. Its biggest weakness is that urgency, small-screen reading, and network interruptions can combine into a poor decision if you rush.
I would recommend approaching it as a comparison tool and possible solution, not as an automatic rescue. Use a trusted connection, verify every important detail, avoid repeated submissions when the network stalls, and keep a backup plan for the bill itself. If repayment is uncertain or the cash gap is part of a repeating pattern, a different route is likely healthier. For the right user and the right limited situation, the app can be useful; for anyone seeking a guaranteed or long-term financial fix, it is not the option I would rely on.
Frequently Asked Questions
What is Money App - Cash Advance, and how does it work?
Money App - Cash Advance is designed to help eligible users access a small amount of money before their regular payday. After creating an account, you typically provide personal, employment, and banking information so the service can evaluate eligibility. If approved, the available advance, fees, repayment date, and transfer method are shown before you confirm the request.
Who can use Money App - Cash Advance?
Eligibility depends on factors such as your age, location, identity verification, income, employment history, and an eligible bank account. Meeting the basic requirements does not guarantee approval, because the app or its lending partners may review additional information. Availability, limits, and terms can also vary by state or country, so users should check the current conditions inside the app.
How much does Money App - Cash Advance cost?
The total cost depends on the advance amount, transfer speed, membership or subscription terms, and any applicable service or optional instant-transfer fees. Before accepting an offer, carefully review the repayment amount, due date, recurring charges, and other disclosures. Do not assume that a cash advance is free, and compare the final cost with other available financial options.
When will I receive the money, and how is repayment handled?
Delivery time may depend on the selected transfer option, your bank, weekends, holidays, and whether additional verification is required. Standard transfers can take longer than expedited ones, which may involve an extra fee. Repayment is generally collected on the date displayed in your agreement, often from the linked bank account, so make sure sufficient funds are available.
Is Money App - Cash Advance safe to use?
The app may use account security features and encryption to protect information, but users should still review its privacy policy, permissions, and the identity of any lending or financial partners. Download it only from an official app store, avoid sharing login codes, and read every agreement before connecting a bank account. A cash advance should be used carefully because missed repayment or recurring fees can create additional financial pressure.


